

You were injured in a car accident, followed your doctor’s treatment recommendations, and expected the insurance company to cover your medical expenses. Instead, the adjuster claims your treatment was unnecessary, too expensive, or unrelated to the collision.
When an insurance company disputes medical treatment, it can delay your claim, reduce your settlement offer, or leave you responsible for unpaid medical bills.
Understanding why insurers challenge medical care, what evidence supports your injuries, and how California law protects accident victims can help you respond to a dispute.
What Does It Mean When an Insurance Company Disputes Medical Treatment?
A medical treatment dispute occurs when an insurer questions whether the care you received was reasonable, necessary, or directly related to your accident.
In California, these disputes usually involve two different types of insurance claims:
- Third-party liability claims: The at-fault driver’s insurance company challenges the medical expenses included in your injury claim.
- First-party insurance claims: Your own insurer questions whether treatment qualifies for payment under your policy, such as optional medical payments (MedPay) coverage.
Unlike your own medical payments coverage, the at-fault driver’s liability insurance does not pay medical bills as treatment occurs. Instead, the insurer evaluates those expenses when determining a potential settlement.
Treatment Dispute vs. Medical Bill Dispute vs. Claim Denial
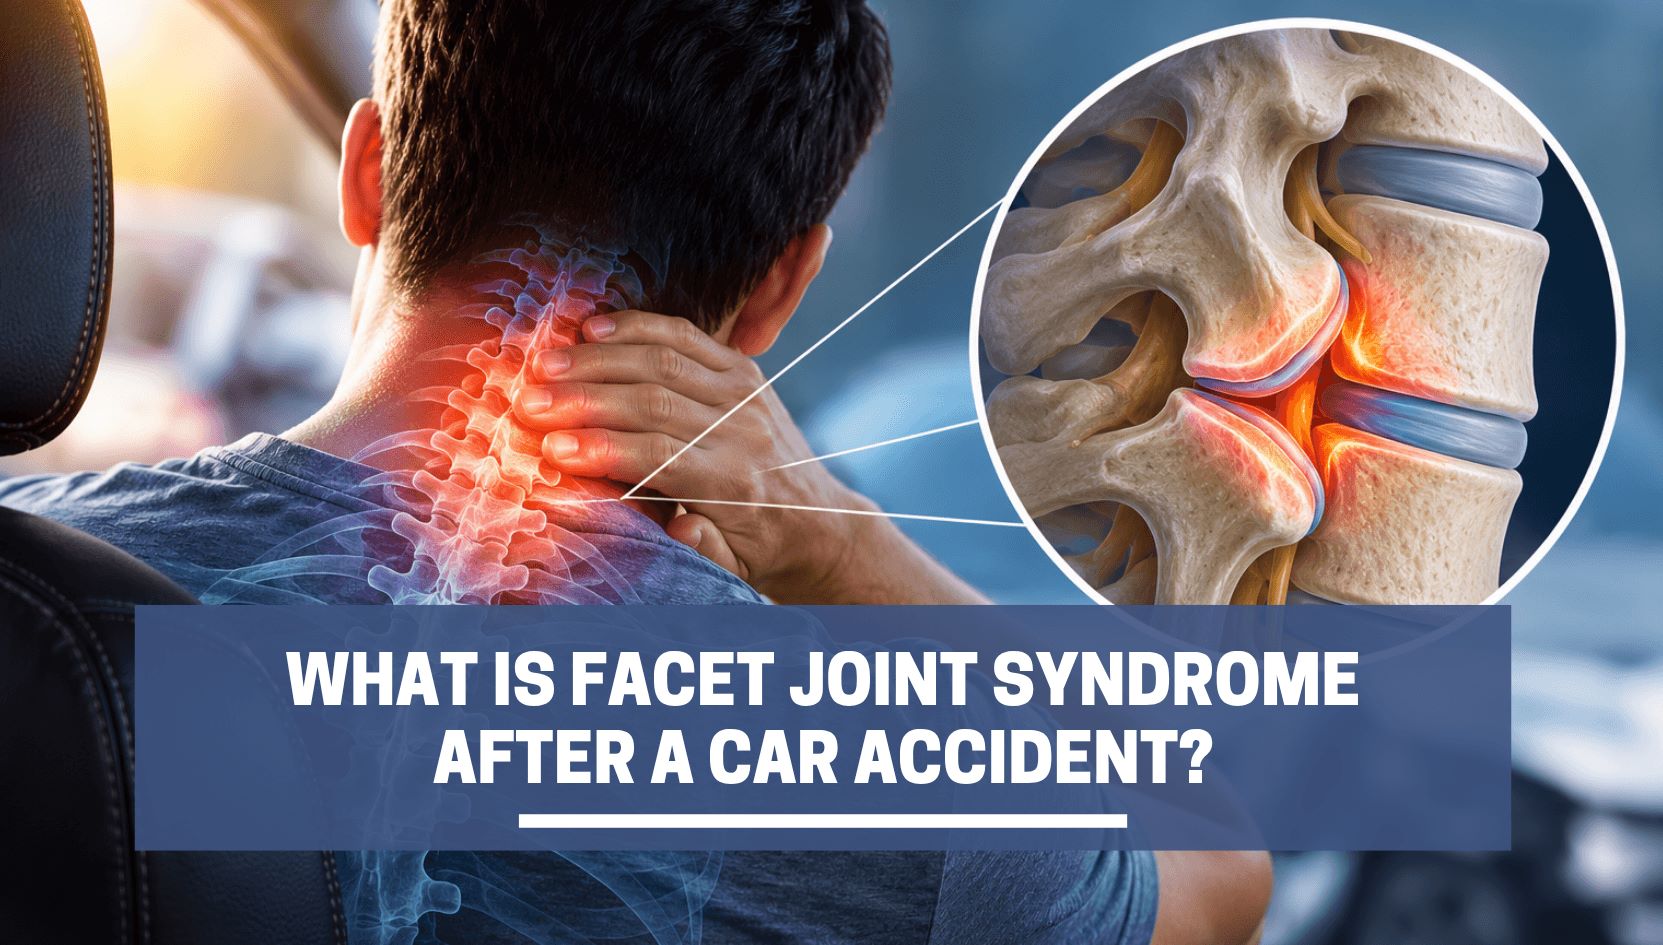
| Symptom | Cervical Facet Joint Syndrome (Neck) | Lower Facet Joint Syndrome (Lower Back) |
| Pain Location | Neck, shoulders, or upper back | Lower back, buttocks, or hips |
| Referred Pain | Headaches or shoulder discomfort | Pain extending into the upper thigh |
| Pain Triggers | Turning or extending the neck | Twisting, standing, or bending backward |
| Stiffness | Difficulty turning the head | Reduced lower back flexibility |
| Common Limitations | Driving, looking upward, or desk work | Standing, lifting, or walking |
Cervical Facet Joint Syndrome (Neck): Neck, shoulders, or upper back
Lower Facet Joint Syndrome (Lower Back): Lower back, buttocks, or hips
Cervical Facet Joint Syndrome (Neck): Headaches or shoulder discomfort
Lower Facet Joint Syndrome (Lower Back): Pain extending into the upper thigh
Cervical Facet Joint Syndrome (Neck): Turning or extending the neck
Lower Facet Joint Syndrome (Lower Back): Twisting, standing, or bending backward
Cervical Facet Joint Syndrome (Neck): Difficulty turning the head
Lower Facet Joint Syndrome (Lower Back): Reduced lower back flexibility
Cervical Facet Joint Syndrome (Neck): Driving, looking upward, or desk work
Lower Facet Joint Syndrome (Lower Back): Standing, lifting, or walking
An insurance company disputes medical bills by challenging the amount charged rather than the underlying treatment. An insurer may also issue an insurance reservation of rights letter while investigating whether a claim falls within the policy’s coverage.
Receiving this letter does not necessarily mean your claim has been denied.
Why Do Insurance Companies Dispute Medical Treatment After a Car Accident?
Insurance adjusters review medical records, diagnostic tests, treatment plans, and accident reports to determine whether the claimed expenses are justified. Common reasons for disputed medical treatment after a car accident include:
Delayed Symptoms or Gaps in Treatment
Not every accident injury causes immediate symptoms. Some people feel little discomfort at first but later develop neck pain, headaches, or stiffness.
However, an insurer may question whether symptoms appearing several days after a collision were caused by the accident. Understanding delayed pain after a car accident can help explain why prompt medical evaluations and accurate symptom documentation matter.
Insurers may also challenge claims with long gaps between appointments, especially when medical records don’t explain the interruption.
Injuries That Are Difficult to Confirm Through Imaging
Soft tissue injuries involving muscles, ligaments, and tendons may not appear clearly on standard X-rays. For example, an insurer reviewing a whiplash injury claim may question the severity of neck pain when diagnostic imaging shows no fractures or obvious structural damage. However, a normal X-ray does not necessarily rule out a soft tissue injury.
Treatment Considered Excessive or Unnecessary
An insurer may agree that you suffered an injury but disagree with the amount or type of treatment recommended.
Disputed expenses may include:
- Repeated physical therapy or chiropractic appointments
- MRI scans, CT scans, and other diagnostic tests
- Pain management injections
- Specialist consultations and referrals
- Surgery and projected future medical care
The insurer may argue that less expensive treatment would have been sufficient or that continued care was no longer medically necessary.
Pre-Existing Medical Conditions
Insurance companies may review previous medical records to determine whether symptoms existed before the collision. For example, an adjuster might attribute back pain to degenerative disc disease rather than the accident.
Disagreements can also arise over the diagnosis itself, such as the distinction between bulging and herniated discs after a car accident.
How Do Insurance Companies Evaluate Medical Evidence?
When reviewing a California car accident claim, adjusters compare the circumstances of the collision with the injuries, diagnoses, and treatment documented in your medical records.
They may consider:
- Timing of treatment: How soon you sought medical attention after the accident.
- Medical diagnoses: Whether your doctor’s findings support the reported injuries.
- Diagnostic tests: Whether X-rays, MRIs, or other tests identify relevant injuries.
- Treatment recommendations: Whether your physician explains why particular procedures or therapies were necessary.
- Treatment consistency: Whether your medical history documents continuing symptoms and follow-up care.
- Accident circumstances: Whether the collision’s reported forces and mechanism are consistent with the injuries.
For example, a driver injured in a California rear-end collision may experience neck pain and headaches. An insurer might question the connection if the driver waited several weeks before seeking treatment.
In some cases, insurers may request an independent medical examination or additional records. Whether an examination is required depends on the policy, applicable law, and the claim’s circumstances.
What About Serious Injuries?
Even serious injuries, including spinal cord injuries from car accidents, can lead to disputes over the necessity and cost of ongoing medical treatment.
Can an Insurance Company Deny Treatment Because of a Pre-Existing Condition?
Under the Judicial Council of California’s Civil Jury Instruction CACI No. 3927, an injured person may recover damages for the worsening of a pre-existing condition caused by another party’s wrongful conduct.
For example, someone with occasional back discomfort before a collision might experience worse symptoms afterward, requiring additional treatment. The central question is whether the accident measurably worsened the existing condition.
Medical records documenting symptoms, physical limitations, and treatment before and after the crash can help establish that connection.
What Evidence Can Support Disputed Medical Treatment?
Strong medical documentation can help demonstrate why treatment was necessary and how injuries relate to the collision. Useful evidence includes:
- Treating physician notes: Document diagnoses, symptoms, examination findings, and treatment recommendations.
- Diagnostic imaging: Provides findings that may support certain injuries.
- Specialist referrals: Explains why additional evaluations or treatment were recommended.
- Medical bills: Identifies services provided, treatment dates, and associated charges.
- Previous medical records: Establishes whether an existing condition worsened after the accident.
- Personal symptom journal: Records pain, physical limitations, and difficulties with everyday activities.
Together, these records can establish when symptoms began, how the injuries affected daily activities, and why specific treatments were recommended. A treating physician’s explanation can be helpful when an insurer questions whether the accident caused the injuries or whether continued care was necessary.
What Should You Do If an Insurance Company Disputes Your Treatment?
Taking the following steps can help protect your claim.
- Request a written explanation: Ask the insurer to identify which treatments or charges it disputes and why.
- Review your medical records: Check for missing appointments, inaccurate information, or incomplete treatment histories.
- Speak with your treating physician: Ask whether additional documentation can explain the medical necessity of disputed treatment.
- Continue medically recommended care: Discuss treatment decisions with your doctor rather than stopping care solely because an insurer questions payment.
- Keep detailed records: Save correspondence, medical bills, insurance notices, and notes from conversations with adjusters.
- Explore payment options: Ask providers about payment arrangements, applicable health insurance, or medical liens while your claim remains unresolved.
Be cautious about signing broad medical authorizations or providing recorded statements without understanding how the information may be used.
Does California Require Insurance Companies to Respond Within Certain Deadlines?
Yes. California’s Fair Claims Settlement Practices Regulations establish deadlines for acknowledging claims, responding to communications, and making claim decisions.
Insurers must:
- Respond within 15 calendar days to communications from claimants that reasonably require a response.
- Acknowledge a claim within 15 calendar days of receiving notice and begin the investigation.
- Accept or deny a claim within 40 calendar days after receiving proof of claim, subject to applicable exceptions and additional investigation requirements.
If an insurer needs more time to investigate, it must provide a written explanation and required updates. These deadlines do not necessarily mean a disputed personal injury settlement must be finalized within 40 days.
Consumers concerned about improper claim handling can contact the California Department of Insurance at 1-800-927-4357.
How Can Disputed Medical Treatment Affect Your Settlement?
Medical expenses are an important component of personal injury compensation. If an insurer disputes treatment, it may exclude certain expenses from its settlement calculation or offer less than the amount requested. For example, an insurer might accept emergency room charges but challenge several months of physical therapy.
These disagreements can affect compensation sought for medical expenses, future treatment, and pain and suffering. However, the insurer’s initial valuation does not necessarily establish the amount an injured person is legally entitled to recover.
Understanding the California car accident settlement process can show how medical evidence shapes negotiations.
Get Help When an Insurance Company Disputes Your Medical Treatment
An insurance company’s decision to dispute your treatment does not mean you must accept a reduced settlement. Medical records, physician recommendations, and other evidence can help establish the connection between your injuries and the accident.
California courts require personal injury lawsuits to be filed within two years of the injury, though exceptions and shorter deadlines may apply. Consulting a personal injury lawyer after a car accident can help you understand your options when an insurer disputes necessary treatment.
If an insurer is questioning your injuries, disputing medical expenses, or delaying your claim, contact The Shirvanian Law Firm for a free consultation. Our California car accident attorneys can review your case, explain your legal options, and help you pursue the compensation you deserve.